Term Life Insurance BMI and Weight Charts: Rates and Limits (2026 Guide)

Short answer: being overweight does not automatically prevent you from getting term life insurance. Many insurers use height and weight bands, with higher premiums above their Standard limits. Published options narrow in the mid-to-high 40s, but an individual review may still be available.
This guide gives the actual numbers: the BMI each rate class needs, the charts insurers use, what happens above the limits, and the small rules that decide which side of a line you land on. If you're still deciding whether this type of cover suits you, start with what is term life insurance.
Contents
- Can you get term life insurance if you're overweight?
- How do life insurers assess your weight?
- What BMI do you need for each rate class?
- Height and weight chart: find your BMI
- What happens if your BMI is above the limit?
- Why do life insurers give different answers at the same BMI?
- Can you be declined for being underweight?
- Six underwriting rules that change your term life rate
- Can other health conditions affect your weight rating?
- How to get the best term life rate at your weight
- What to do if you're declined for term life insurance
- Eleos for term life when you're overweight
Can you get term life insurance if you're overweight?
Yes, and the range is wider than most people assume.
Insurers don't run a single pass/fail line on weight. They run a ladder. At the top are the best prices with the tightest limits. Below those sit standard rates. Below those, a series of rated bands where you pay a percentage extra. Within the same policy, the payout and term do not change because of a table rating. Other policy features can still differ by product.
Across published underwriting guides, Standard limits end somewhere between a BMI of 35.7 and 40.9, depending on the company. Above that, a fully underwritten carrier may use a table rating, with published ladders reaching roughly 46 to 49. Beyond a published ladder, the carrier may request an individual review or decline the application.
How do life insurers assess your weight?
Three things explain most of the confusing outcomes.
The height-and-weight chart is really a BMI chart
Many insurers publish maximum weights by height for each rate class. Convert those to BMI and something becomes clear: each class sits at a near-constant BMI whatever your height.
On one insurer's chart the standard ceiling works out at 37.9 to 38.0 across all 26 heights from 4'8" to 6'9". A chart that looks like 26 separate rules is one rule written 26 times.
That's useful. You only need to know your BMI, not find your row.
The steps between bands are small
Moving up a rated band costs a set percentage. On one insurer's ladder, each step buys exactly one more point of BMI:
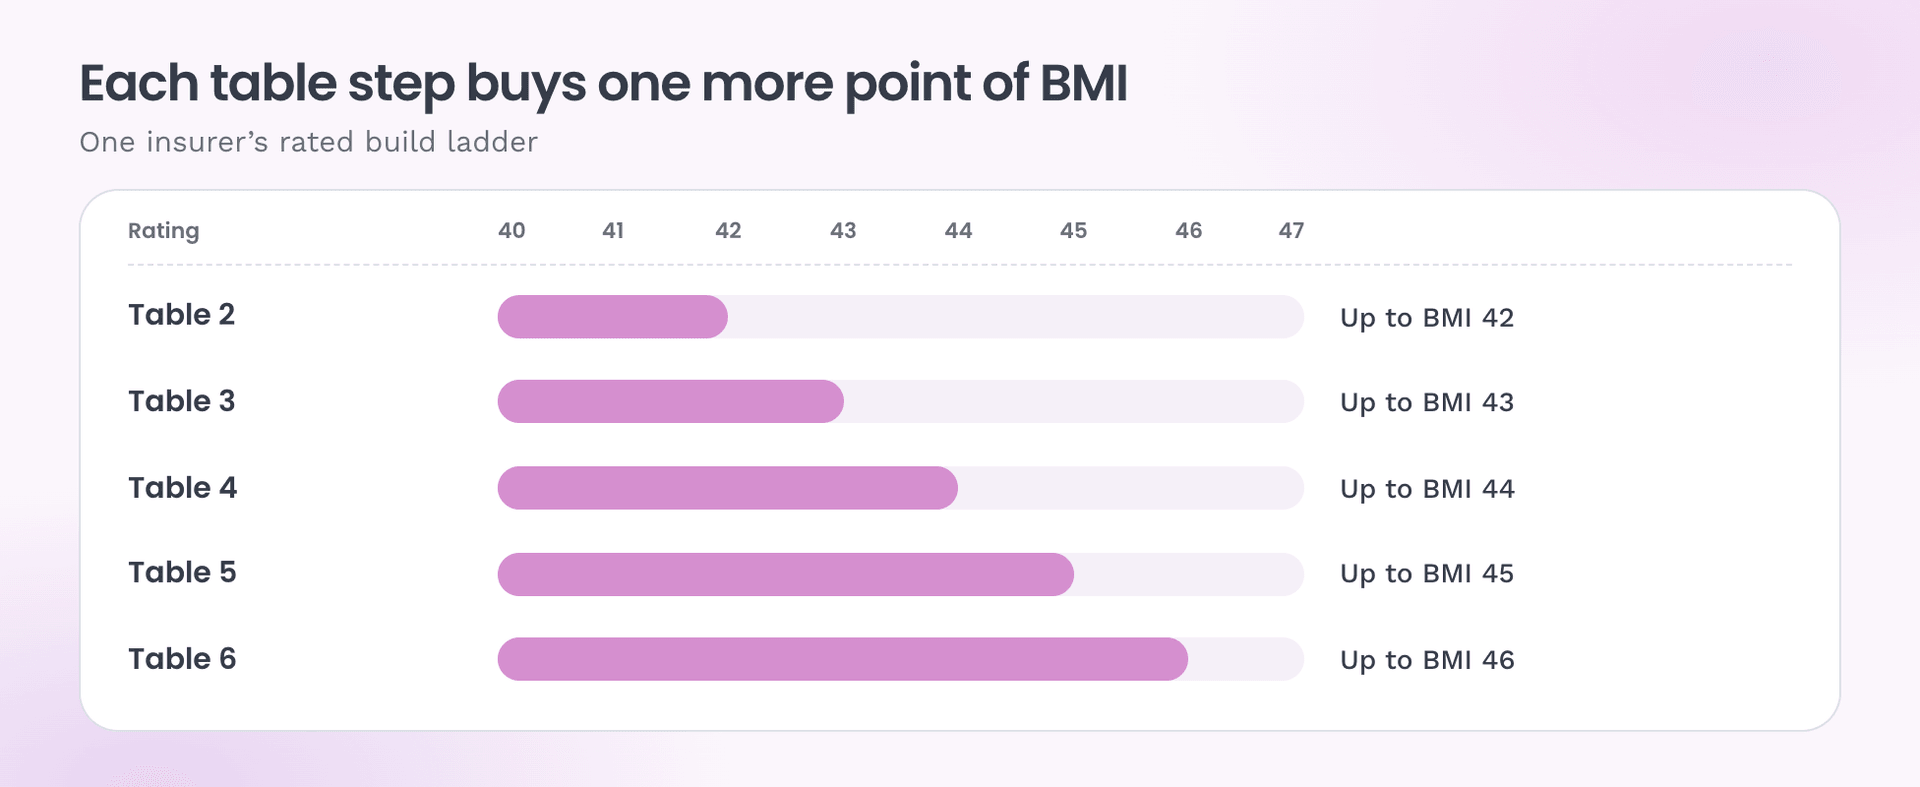
On that carrier's published chart, being a few pounds over a line usually moves the application one table rather than automatically ending eligibility. The rest of the health history still matters.
Simplified and fully underwritten products behave differently
A simplified-issue policy typically asks fewer health questions and may use firm eligibility limits. It often has no table ratings available, although product designs vary.
A fully underwritten policy can use medical records, data checks, lab work or an exam. It may have more rated classes available and can sometimes make an individual decision instead of applying a simple cutoff. Fully underwritten does not always mean an exam is required.
That is why a decline from a fast online application does not necessarily mean the broader market will decline the same person. The next carrier will still evaluate the complete application.
What BMI do you need for each rate class?
Converted from published carrier height-and-weight charts. Where carriers differ, the range is shown.
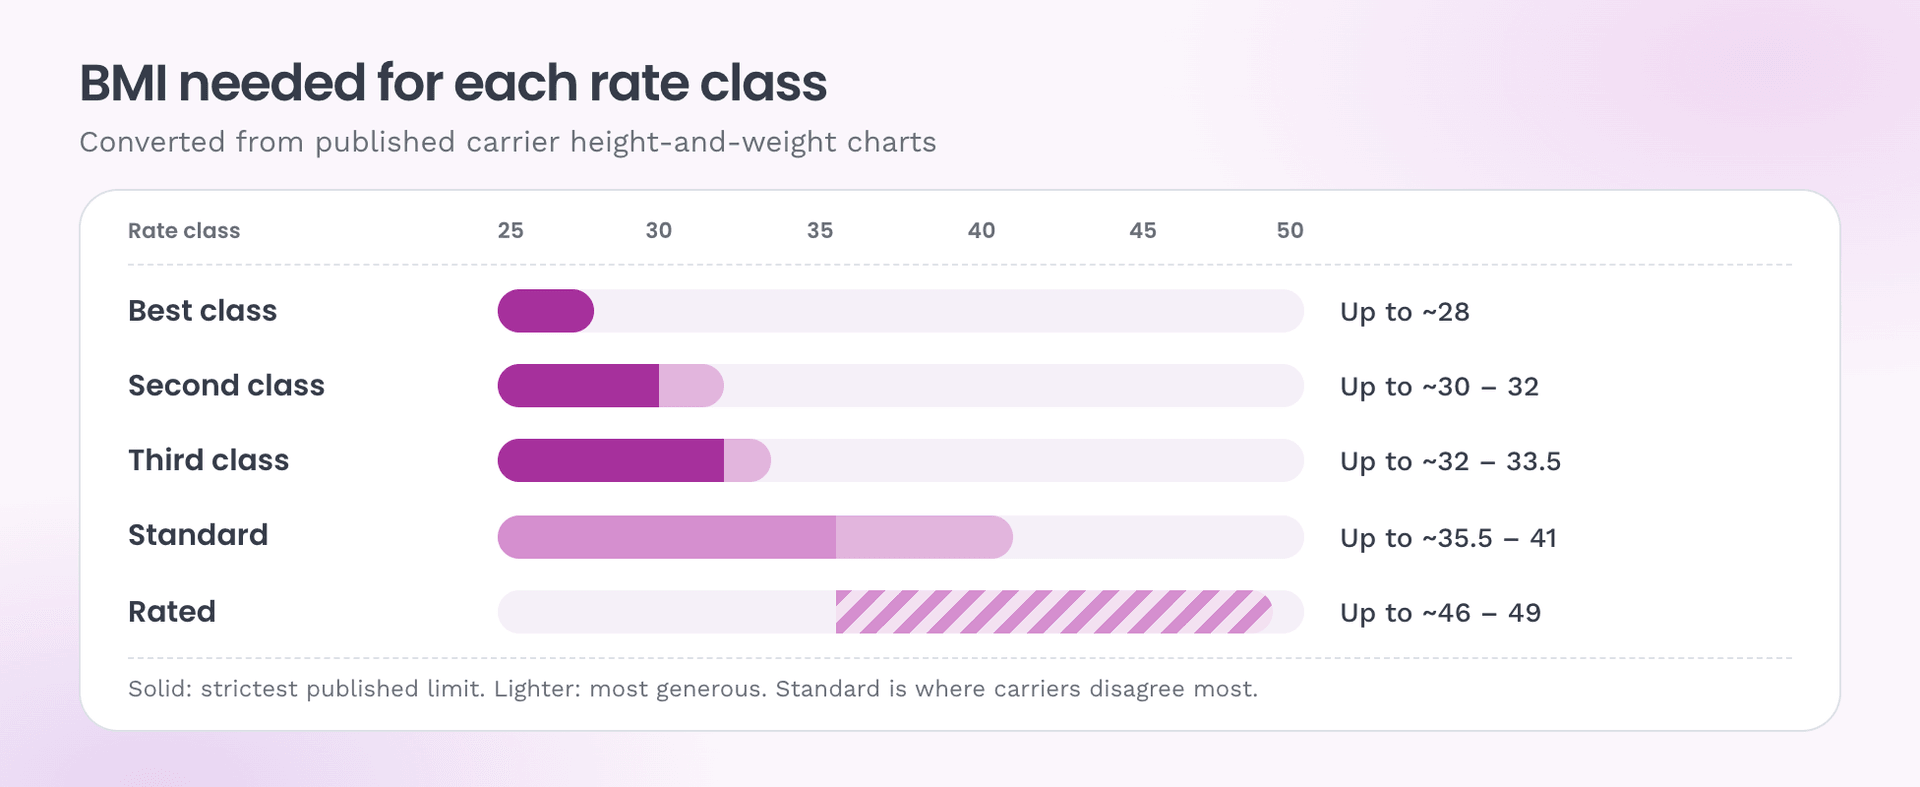
| Rate class | BMI needed | Notes |
|---|---|---|
| Best class | up to ~28 | Lowest price available. Also needs everything else clean. |
| Second class | up to ~30 – 32 | Still a preferred price, meaningfully under Standard. |
| Third class | up to ~32 – 33.5 | Not offered by every insurer. |
| Standard | 35.5 – 41 | The reference price. Where most people land. |
| Rated bands | from your insurer's Standard ceiling to ~46 – 49 | Standard price plus a percentage. |
The top of that table is the striking part. Every published chart reviewed puts its best class at almost exactly the same place: a BMI of 28.1, 28.4 and 28.5. Carriers agree on where excellence starts.
They stop agreeing immediately afterwards.
Height and weight chart: find your BMI
BMI is 703 × weight in pounds ÷ (height in inches)². Or find your height and read across.
| Height | BMI 28 | BMI 30 | BMI 33 | BMI 36 | BMI 38 | BMI 42 | BMI 46 |
|---|---|---|---|---|---|---|---|
| 4'10" | 134 | 144 | 158 | 172 | 182 | 201 | 220 |
| 4'11" | 139 | 149 | 163 | 178 | 188 | 208 | 228 |
| 5'0" | 143 | 154 | 169 | 184 | 195 | 215 | 236 |
| 5'1" | 148 | 159 | 175 | 191 | 201 | 222 | 243 |
| 5'2" | 153 | 164 | 180 | 197 | 208 | 230 | 252 |
| 5'3" | 158 | 169 | 186 | 203 | 215 | 237 | 260 |
| 5'4" | 163 | 175 | 192 | 210 | 221 | 245 | 268 |
| 5'5" | 168 | 180 | 198 | 216 | 228 | 252 | 276 |
| 5'6" | 173 | 186 | 204 | 223 | 235 | 260 | 285 |
| 5'7" | 179 | 192 | 211 | 230 | 243 | 268 | 294 |
| 5'8" | 184 | 197 | 217 | 237 | 250 | 276 | 303 |
| 5'9" | 190 | 203 | 223 | 244 | 257 | 284 | 312 |
| 5'10" | 195 | 209 | 230 | 251 | 265 | 293 | 321 |
| 5'11" | 201 | 215 | 237 | 258 | 272 | 301 | 330 |
| 6'0" | 206 | 221 | 243 | 265 | 280 | 310 | 339 |
| 6'1" | 212 | 227 | 250 | 273 | 288 | 318 | 349 |
| 6'2" | 218 | 234 | 257 | 280 | 296 | 327 | 358 |
| 6'3" | 224 | 240 | 264 | 288 | 304 | 336 | 368 |
| 6'4" | 230 | 246 | 271 | 296 | 312 | 345 | 378 |
| 6'5" | 236 | 253 | 278 | 304 | 320 | 354 | 388 |
| 6'6" | 242 | 260 | 286 | 312 | 329 | 363 | 398 |
Weights are in pounds and rounded to the nearest pound. Find the two weights that bracket your weight. Your BMI is approximately between those column headings. If your weight matches a value, use that column's BMI.
What happens if your BMI is above the limit?
This is the section most guides skip, and it's the one that matters above 40.
Above Standard, many fully underwritten products rate an applicant rather than automatically declining. A rating adds a percentage to a base premium. Simplified-issue products may instead use a firm eligibility cutoff.
Ratings rise in steps. One carrier's build-rating chart starts at +25% for BMI 36.1 to 38.0, then climbs through +50%, +75%, +100%, +125%, +150%, +175% and +200%, with the top published band reaching BMI 48. Its separate rate-class chart can still label some applicants in that range Standard, so a build rating and a named rate class are not always interchangeable.
One insurer in the research calculates substandard premiums from its Standard Plus rate rather than its Standard rate. Always ask which base rate a quoted percentage uses.
Published ladders end at different points:
- One tops out at BMI ~46, above which it becomes an individual underwriting decision rather than an automatic refusal.
- One tops out at BMI ~48 with ratings to +200%.
- One reaches BMI ~49 and offers ratings all the way to +300%, giving it more room at the top than the others.
So "am I too heavy for life insurance?" has no single answer. At a BMI of 45, all three examples are above their Standard limits, but they can assign different ratings and one is close to its published referral point.
Why do life insurers give different answers at the same BMI?
Three published carrier charts, all treating the same person differently.
| Best class | Second | Third | Standard | Top of published ladder | |
|---|---|---|---|---|---|
| Insurer A | 28.4 | 30.4 | Not offered | 38.0 | ~48 (ratings to +200%) |
| Insurer B | 28.1 | 30.1 | 32.4 | 37.9 / 40.9 * | ~46, then individual review |
| Insurer C | 28.5 | 31.7 | 33.3 | 35.7 | ~49 (ratings to +300%) |
* Insurer B publishes two standard bands: the lower one qualifies for a height adjustment and underwriting credits, the higher one doesn't.
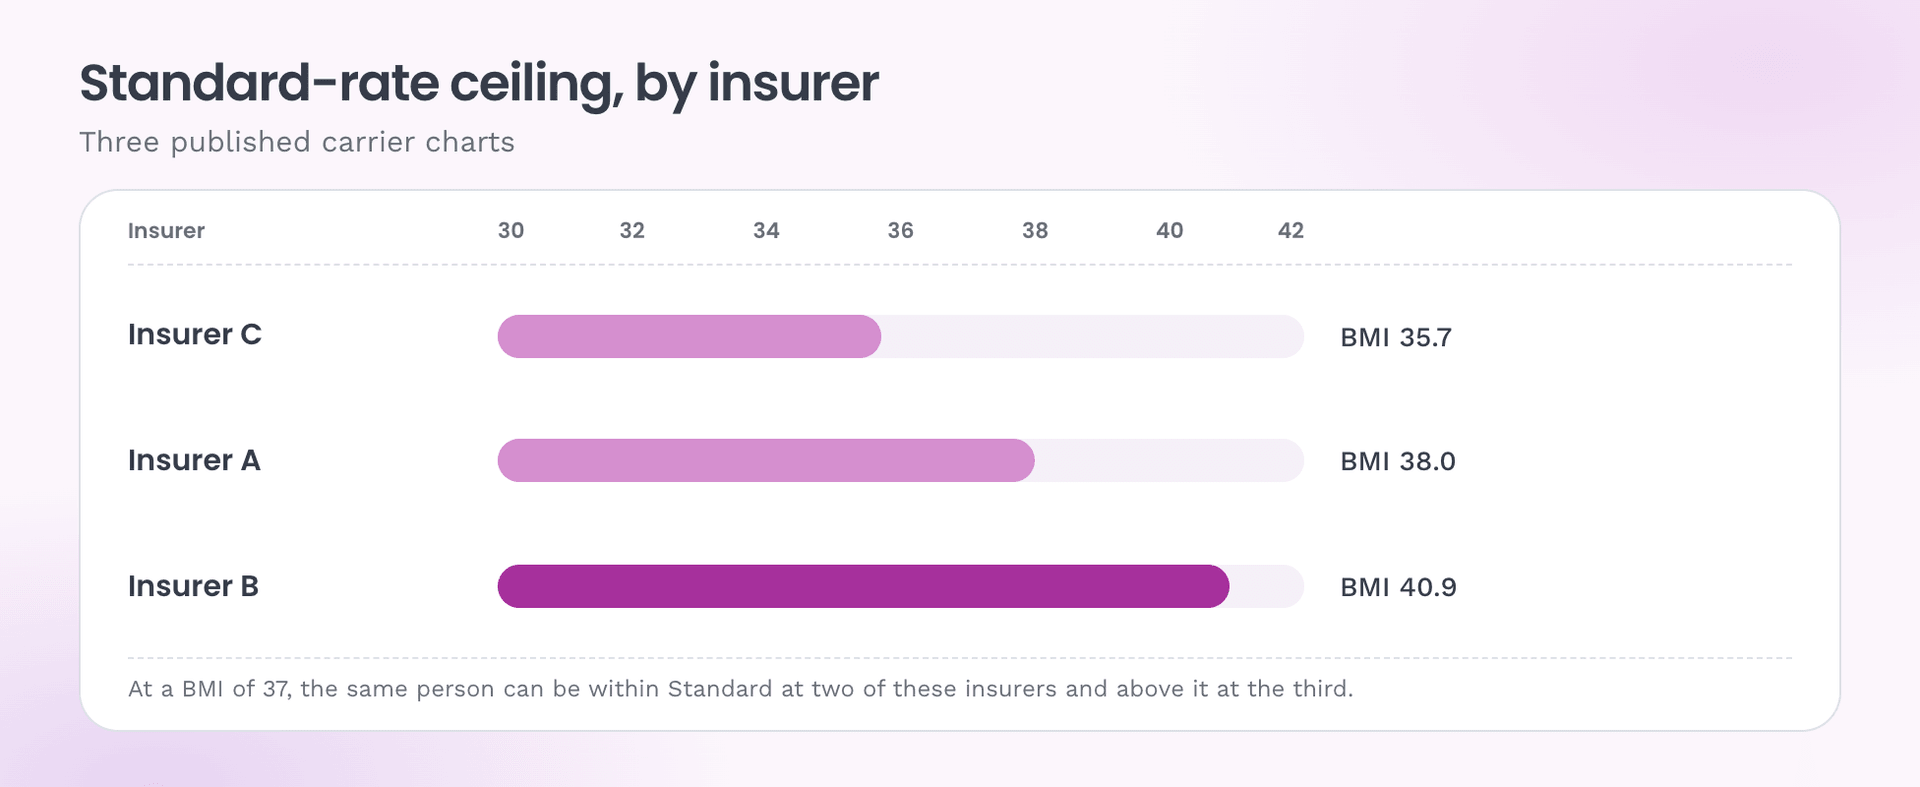
At a BMI of 37, the same person can fall within Standard limits at two of these insurers and above the Standard limit at the third. The difference is the carrier's chart, although the final offer still depends on the full application.
Note the shape of it. Insurer C is the strictest about standard rates and has the most room at the top of its ladder. Being tough at one end doesn't mean being tough at the other. That's why "which insurer is best if you're overweight" is the wrong question. The right one is which is best at your specific number.
Can you be declined for being underweight?
Yes. Insurers may set minimum weights as well as maximums.
The following age bands come from one carrier's published chart and illustrate how the treatment can change:
| Your age | How a low BMI is treated |
|---|---|
| Under 55 | BMI 15.1 to 17.0 is rated; below 15.1 is declined. |
| 55 – 70 | The same low build attracts a smaller rating than it would under 55. |
| 71 and over | Below BMI 21.1 is declined on this chart. |
Two things follow.
Age can change the result. The same low BMI may receive a smaller rating at age 60 than at age 40 on this carrier's chart. At age 71 and older, its low-weight tolerance narrows sharply.
They care about the cause, not the number. Insurers ask why the build is low: unintentional weight loss, an underlying condition, or a naturally light frame. Someone who has always been slight is in a very different position from someone who has lost 25 lb without meaning to. The second is the flag, whatever the scale says.
Another carrier sends weights below its chart minimum or BMI 18.5 to an underwriter. In practice, a low BMI often leads to questions about the cause rather than one universal result.
Six underwriting rules that change your term life rate
Small print, real consequences.
1. Recent weight loss only half counts
One carrier adds back half of intentional weight loss over 20 lb in the previous 12 months, whether the loss came from diet, exercise or surgery.
Lose 30 lb and you're assessed as though you'd lost 15. The logic is that recent loss often reverses, and they're pricing decades of risk.
What to do: report your current and previous weight accurately. If you are near a class boundary, ask whether the carrier's recent-weight-loss rule applies before deciding when to apply. Do not delay needed coverage solely to chase a different rate class.
2. Half-inches round up
One carrier rounds a half-inch up, so 5'9½" is treated as 5'10". Get measured accurately rather than relying on an old driver's license.
3. There's an extra inch available, and it's build's own escape hatch
Separately from its rounding rule, one carrier checks whether a one-inch height adjustment can improve an eligible applicant by one rate class. At around 5'10", one inch can change the weight allowance by roughly 7 lb.
One insurer's own worked example: an applicant meets every requirement for the best class except build, at 5'9" and 195 lb, which places them one class down. At 5'10" and 195 lb, they qualify for the top class.
For that carrier, the credit is available across all ages and policy amounts and for tobacco and non-tobacco applicants. It is the only credit available through that carrier's exam-free route.
4. Favorable health factors can improve a class
One carrier can improve an eligible applicant by one class when enough favorable factors are present. Its criteria include long-term non-tobacco use, favorable cholesterol results, normal recent cardiac testing, family longevity, regular preventive care and certain lab results. These are underwriting credits, not a reason to order unnecessary medical tests.
5. But credits stop at the standard boundary
That carrier's credit program applies only to applications eligible for Standard or better. It does not apply to substandard classes.
That makes the boundary between standard and rated the one worth targeting. A pound either side of it decides whether the whole credit system is available to you or not.
6. Weight-loss surgery has a waiting period
Published carrier guides use waiting periods of six to 12 months after bariatric or gastric bypass surgery. After a one-year postponement, one carrier lists a possible Table 2 to Table 4 rating. The decision still depends on current weight, stability and overall health.
Can other health conditions affect your weight rating?
Sometimes the deciding issue is not weight alone but weight plus something else.
One simplified-issue guide uses specific combination rules. The examples below apply to that product, not to every insurer:
| Combination | Typical outcome on a simplified product |
|---|---|
| Table 2 or higher build + high blood pressure | Declined |
| Table 2 or higher build + peripheral vascular disease | Declined |
| Table 2 or higher build + asthma + tobacco | Declined |
| Table 2 or higher build + diabetes over 45 * | Declined |
* In California and the Virgin Islands that age threshold is 50 rather than 45.
The pattern is not simply how many conditions appear on the application. The product considers the specific combination and the total expected rating.
Two of those factors have guides of their own. Our guide to term life insurance with high blood pressure covers the readings each rate class needs and how medication is treated, and our guide to term life insurance for diabetics covers how type, age at diagnosis, control and complications are assessed.
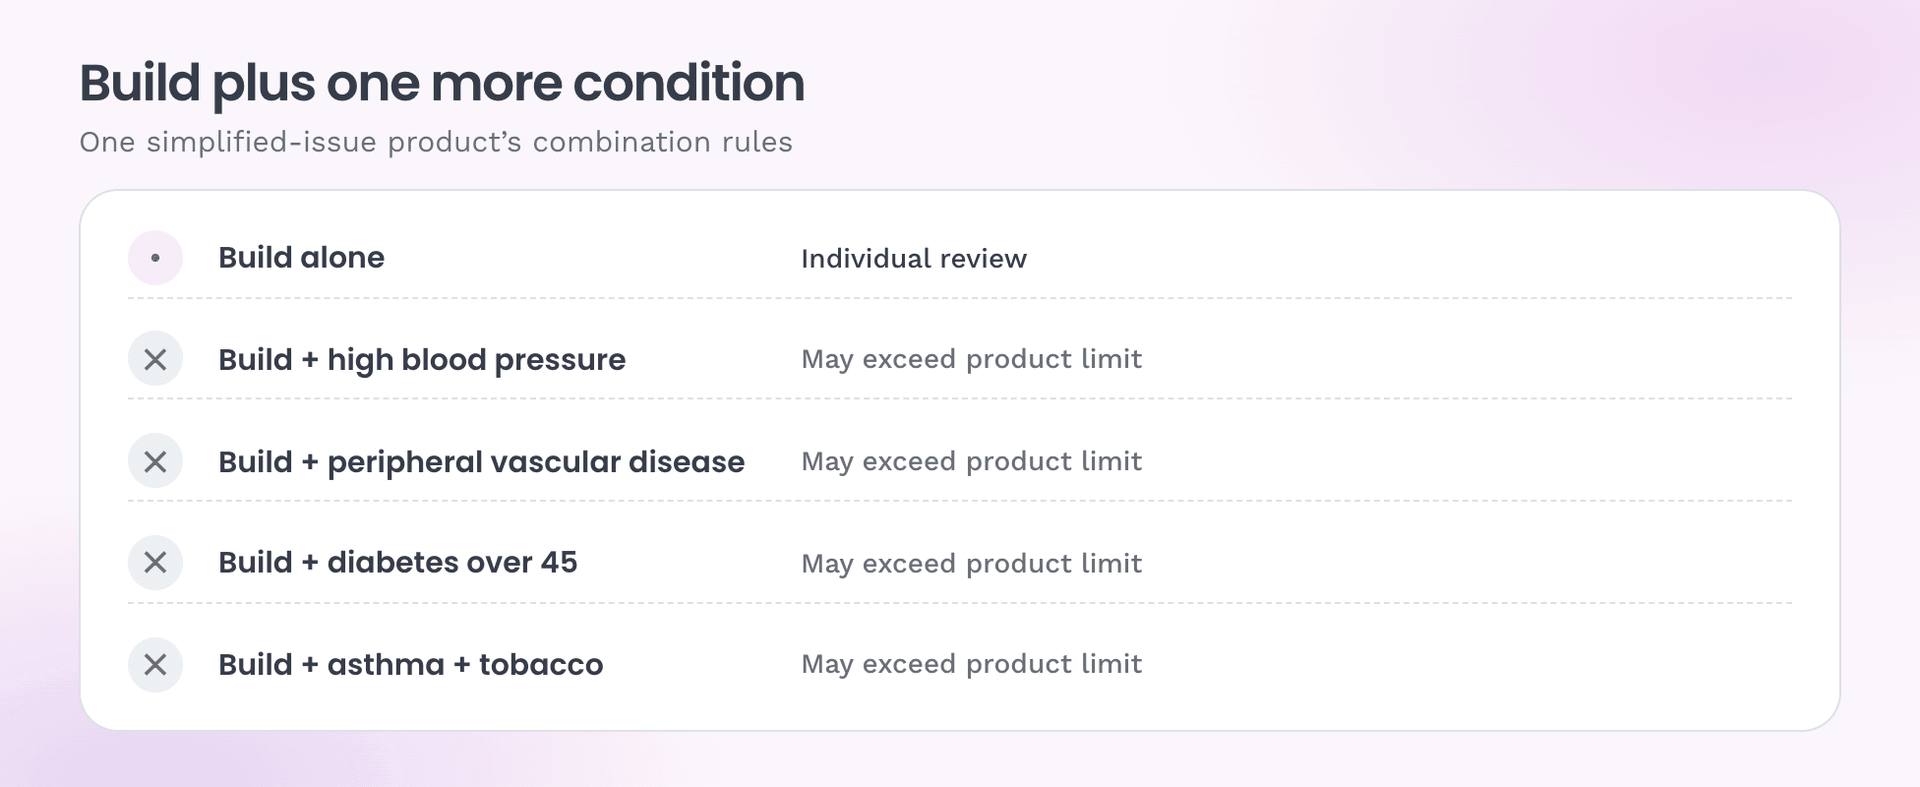
There is a rule behind the list. One insurer states it directly: multiple impairments resulting in a rating greater than Table 4 will be declined on its simplified products.
Ratings can be cumulative. In this guide's examples, a Table 2 build leaves limited room before the product's Table 4 ceiling. Another impairment can push the combined assessment beyond that limit.
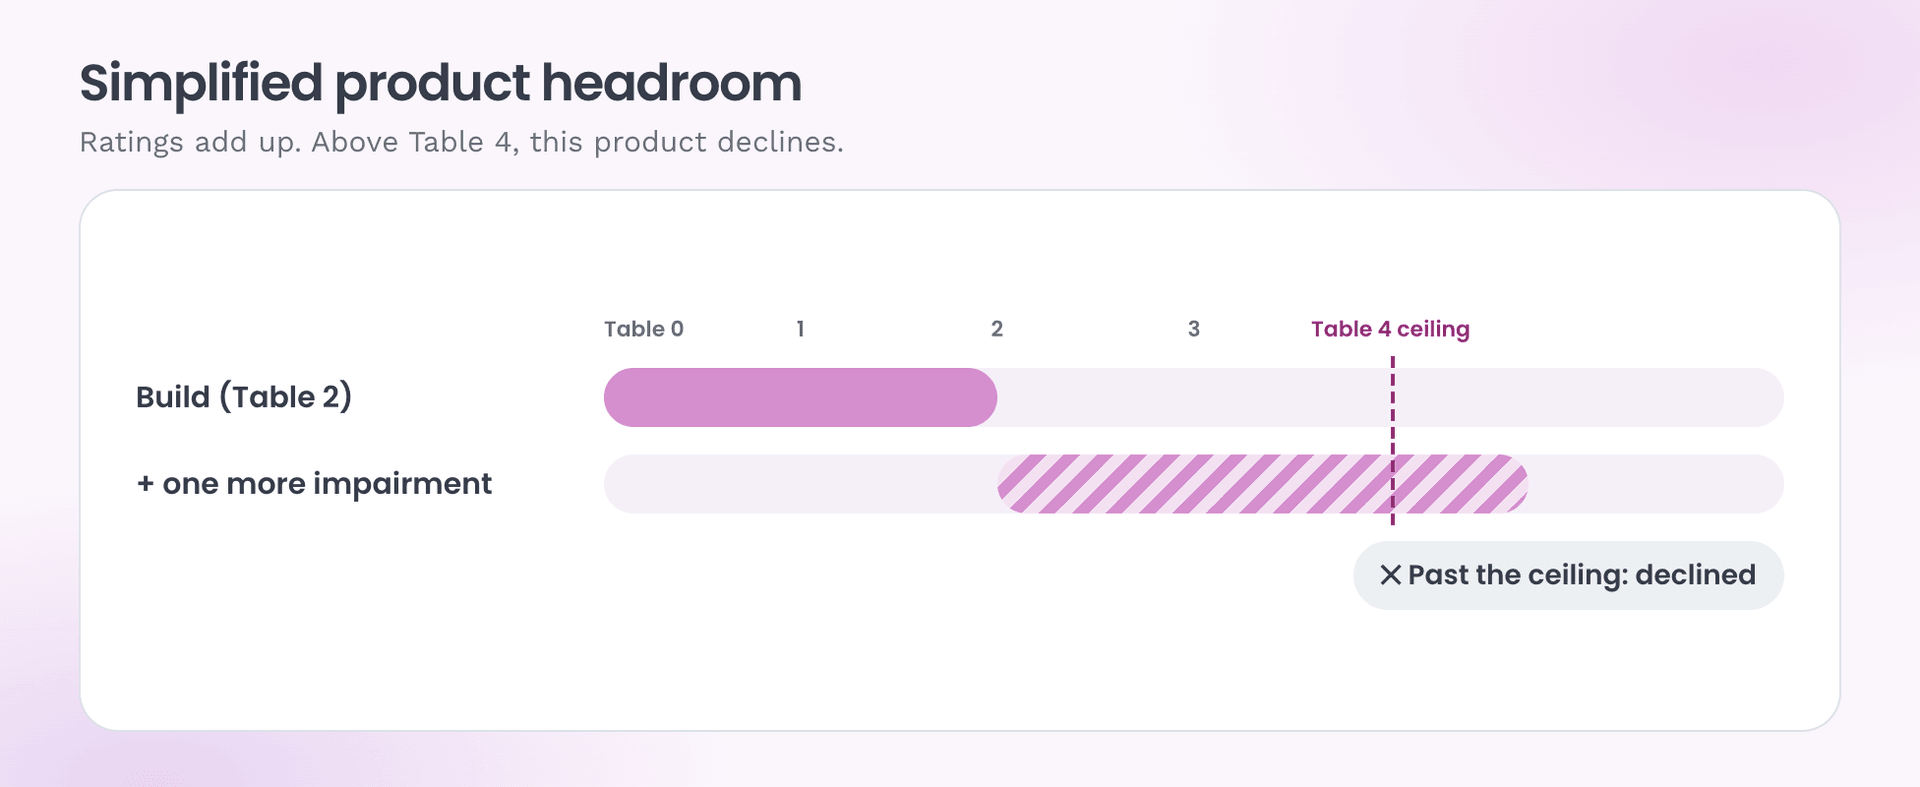
This is one reason two people with identical BMIs can get different answers. No single item may look serious, but the combination can exceed a particular product's limit.
A fully underwritten policy may have more room to assess combinations individually. If a fast application has declined you, ask an advisor to review the reason before submitting another application.
How to get the best term life rate at your weight
In rough order of impact.
1. Know your number first. Find your BMI in the chart above. Within a couple of points of a boundary? Everything below is worth doing before you apply.
2. Ask about recent weight loss. One carrier adds back half of a loss over 20 lb during the first 12 months. An advisor can tell you whether that rule applies and whether timing matters.
3. Get measured accurately. At least one carrier rounds half-inches up. Use a current measurement instead of guessing.
4. Look at the whole application. Tobacco use, blood pressure, diabetes and other conditions can combine with build. Work with your doctor on health changes and compare carrier rules before applying.
5. Don't assume every no-exam product is the same. If an instant-decision application declined you, a fully underwritten product may have rated bands or individual review that the first product did not offer.
6. Apply where your number fits. The gap between insurers at the same BMI can be a whole rate class. That's about choosing correctly first time, not changing anything about yourself.
What to do if you're declined for term life insurance
A decline from one insurer isn't a decline from the market.
It does not create a permanent bar on buying coverage. Future applications may ask about prior declines, so find out why the first application was declined before submitting another one.
Options, roughly in order:
- A different insurer. Given the spread above, often enough on its own.
- A fully underwritten policy instead of a simplified one, so rated bands become available.
- A no-exam policy built for older applicants, where acceptance rests on health questions and record checks rather than an exam.
- Guaranteed issue coverage, which asks no health questions and does not decline applicants on health grounds. Amounts are usually lower, and natural-cause death may have a waiting period.
- Reapplying later, if you're close to a line and moving the right way.
Eleos for term life when you're overweight
Your BMI doesn't have one answer. Standard limits end at 35.7 on one published chart and 40.9 on another. The number that decides your price is often the door you knocked on, not the one on the scale.
We work with multiple insurers and bring them together into one seamless product. You answer one set of questions. We handle the rest.
- One application. Not a form per insurer, and no trail of declines building on your record.
- We know where the lines sit, including the rated bands and the credit rules most comparison sites never mention.
- We know which products have a firm cutoff and no rated bands, so you don't spend three weeks finding out.
- There's still a route if underwritten coverage isn't available, including options that ask no health questions at all.
And it costs nothing extra. Life insurance rates are filed with state regulators, so you pay the same premium through us as you would going direct.
Start a term life quote online. If build is the sticking point, speak to an advisor first: that's usually faster.
This guide describes how life insurance underwriting generally works, based on the published underwriting rules of the insurers Eleos works with. It isn't advice and it isn't a quote. Individual outcomes depend on your full application. Figures are indicative and current as of August 2026.
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not insurance advice. Product features, availability, and amounts vary by state and by policy. Always review the official plan documents for the full terms, limitations, and exclusions before you buy.
Related resources
Life insurance after a DUI: how long insurers look back
A DUI is priced mostly by time since the offense, the number of offenses and license status. This guide explains look-back periods, flat extras and how to choose a route.
Life insurance with sleep apnea: how CPAP use affects your rate
Sleep apnea rarely blocks life insurance. This guide explains how severity and treatment records shape your rate and which application route to consider.
Life insurance with depression and anxiety: how insurers judge severity
How US life insurers sort depression and anxiety into mild, moderate and severe, what moves your price, and how fully underwritten and no-exam routes differ.
Life insurance with asthma: what insurers look at
How US life insurers judge asthma by severity, attacks, treatment and tobacco use, why a COPD label matters, and whether to apply fully underwritten or no-exam.
Life insurance with high cholesterol: the full picture
How high cholesterol and statins affect life insurance: what insurers measure, where their limits sit, and how to get a better price.
Life insurance after cancer: waiting periods and options
Cancer history doesn't automatically rule out life insurance. Insurers look at type and stage, time since treatment, and recurrence or spread, and their waiting periods vary widely.